![]()
InTek Intermodal Index (III) Weekly Market Analysis
Weekly market intelligence including the InTek Intermodal Index (tracking intermodal spot rates), along with truckload pricing, diesel trends, and railroad volumes
Updated every Thursday | Last updated: October 29, 2026 | View historical archive
This Week at a Glance
Week ending October 26, 2026
Intermodal Spot Rate
(excluding fuel)
▲ +0.2% vs. last week
▲ +7.9% vs. last year
Truckload Spot Rate
(excluding fuel, DAT)
▲ +0.3% vs. last week
▲ +46.8% vs. last year
Diesel Fuel
(EIA National Average)
▲ +1.2% vs. last week
▲ +70.8% vs. last year
Intermodal Volume
(YTD vs. 2025)
U.S. ▲ +4.5%
North American ▲ +3.7%
This Week's Analysis
By Rick LaGore, CEO, InTek Logistics | October 27, 2026
Analysis of the InTek Intermodal Index (III) and freight market trends
Trends in the Intermodal Transportation Spot Rate and Market
Intermodal spot held steady this week while truckload inched up and diesel climbed for a second week. Intermodal spot gained 0.2% and stands 7.9% above last year. Truckload spot added 0.3% and holds 46.8% above last year. Diesel rose 7.6 cents to $6.352, now 70.8% above last year. Year-to-date intermodal volume runs 3.7% ahead of 2025 in North America and 4.5% in the US.
To sum up the week, we had essentially a pause in rates against a growing volume backdrop. Both spot indexes barely moved, so the linehaul spread held where it has sat through October. The shift came from diesel, which turned back up after easing through early October, and from the volume data, where truck-to-rail conversion keeps carrying the growth.
Both spot indexes barely moved, so the linehaul spread did not change. Intermodal's cost base sits 7.9% above last year against truckload's far larger step up, both excluding fuel.
Shippers should price the spread on total cost with fuel included. Diesel at 70.8% above last year keeps fuel the biggest single item in the comparison. It turned back up this week, so watch the 3-2-1 crack spread for where it goes next.
InTek Intermodal Index (excluding fuel):
- Up 0.2% vs. prior week
- Up 7.9% vs. prior year
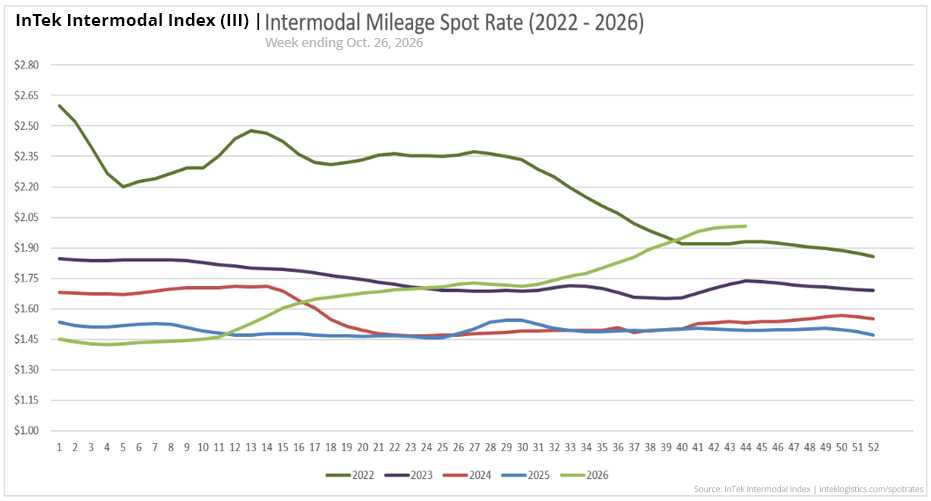
The InTek Intermodal Index (III), which tracks intermodal spot rates, was close to unchanged for the week at 0.2% and holds 7.9% above last year. After a steady run through the quarter, that print reads as a pause at a firm level, not a turn.
The year-over-year figure keeps building. It is the number that tracks how far intermodal's cost base has moved off last year. Drayage stays tight across much of the network, and that first and last leg is where a shipper feels service, rather than the rail move between the ramps.
National Truckload Spot Rate (DAT, excluding fuel): (DAT Trendline Report)
- Up 0.3% vs. prior week
- Up 46.8% vs. prior year
Truckload spot added 0.3% for the week and holds 46.8% above last year. The weekly move is small, and the cost base well above last year keeps the mode gap wide on lanes where both compete. With both indexes barely moved this week, the linehaul spread held steady.
Diesel Fuel (EIA):
- $6.352/gallon
- Up $0.076 (1.2%) vs. prior week
- Up $2.634 (70.8%) vs. prior year
Diesel added 7.6 cents to $6.352 per gallon, up 1.2% on the week and up $2.634 (70.8%) on the year. This is a second straight weekly gain, and it puts the early-October pullback behind us. The drift lower from the September high has turned back up, and the year-over-year gap is above 70% again.
The driver has not changed, which is in refining and distillate supply, not in crude, so the direction tracks refining margins more than the oil price. For a shipper, the 3-2-1 crack spread continues as what to watch for where diesel goes next. Rail is roughly three times more fuel efficient than over-the-road truck on a ton-mile basis. At a 70.8% year-over-year gap, fuel keeps pulling marginal long-haul freight to rail.
(The full spreadsheet of the historical weekly price moves of diesel full can be found at https://www.eia.gov/petroleum/gasdiesel.)
Year-to-Date Intermodal Volume by Region and Railroad vs. 2025
North American intermodal volume runs 3.7% ahead of 2025 year to date and US volume 4.5%, both firming a couple of tenths from last week. The recent pace is stronger than the cumulative figure shows, with the US four-week rate at 10.5% and the steadier 13-week rate at 6.9%. The 13-week read is the better guide, since year-ago comparisons run soft into December and will overstate the four-week prints.
The growth is picking up steam to the west. The Western US networks are up 13.5% on a four-week basis and are taking about two-thirds of the volume gain. The Eastern networks run 5.9% and the Canadian networks 1.7%. GMXT leads the year-to-date table at 11.4%. The recent Mexico surge is in large part a base effect against a weak 2025, instead of a step change in nearshoring. BNSF (5.6%) and CSX (5.3%) sit above the US pace, with NS (4.2%), UP (3.0%), and CPKC (2.0%) positive and CN (-2.6%) the lone holdout below last year.
The import leg is strong, and part of it is borrowed. West Coast ports set monthly records in September as freight moved ahead of year-end, and forecasts have imports rising into October before turning down in November. That pull-forward is the main risk to the international side, and it puts the weight on domestic truck-to-rail conversion to hold the line as imports fade. Scarce truck capacity and diesel back above $6 keep pushing marginal freight to rail, the mechanism underneath the numbers.
North American Intermodal
3.7%
U.S. Intermodal
4.5%
Volume by Railroad
| BNSF | 5.6% |
| CN | -2.6% |
| CPKC | 2% |
| CSX | 5.3% |
| GMXT | 11.4% |
| NS | 4.2% |
| UP | 3% |
Intermodal Spot Rate Trend Charts
Intermodal Spot Rate Per Mile (Including Fuel)
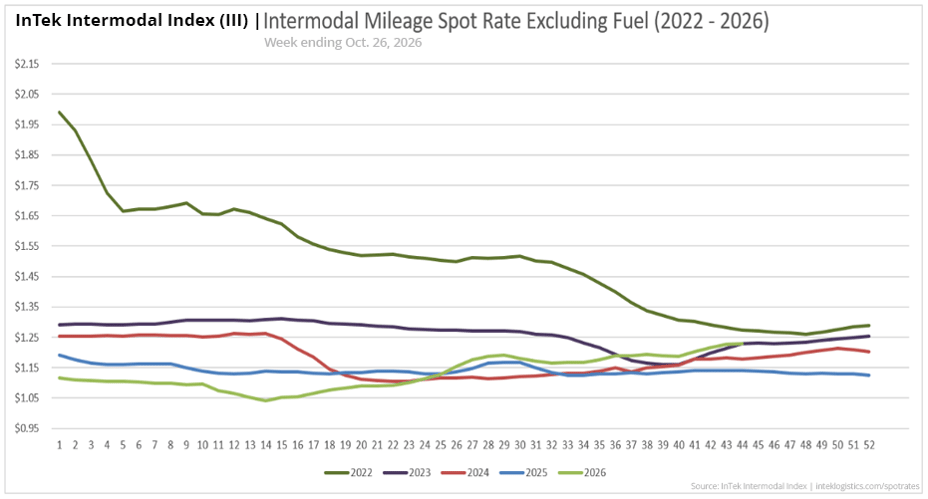
Intermodal Spot Rate Per Mile (Excluding Fuel)
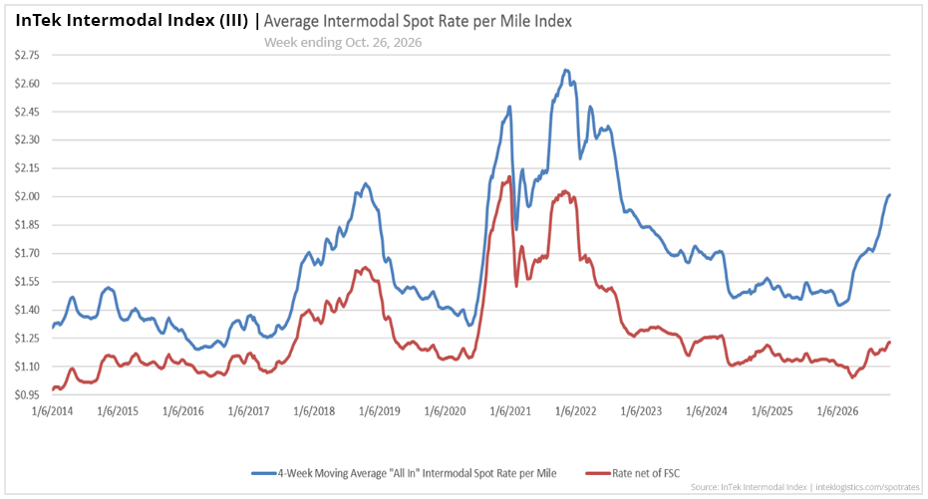
Intermodal Spot Rate Average Per Mile (2014-2026)
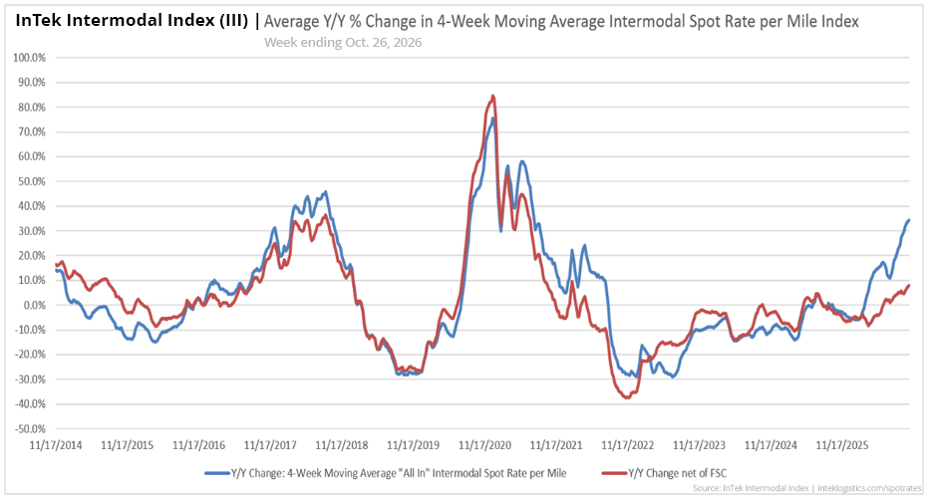
Intermodal Spot Rate Y/Y % Change (2014-2026)
What to watch next week
Three things to watch heading into the week of October 26, 2026.
Does intermodal spot resume, or has it stalled?
Spot has risen through the quarter but came in near flat this week. Watch whether it picks back up or settles here as peak pricing matures. A second quiet week would say the seasonal push has run its course for now.
Does diesel keep climbing?
Diesel has turned back up for two straight weeks and sits above $6.35. Watch the next EIA print and the crack spread for whether this is a short move or a return toward the September high. As long as it holds up here, fuel keeps widening the intermodal advantage.
Does domestic conversion hold as imports roll off?
Import volume is set to turn down in November after a strong, partly front-loaded run. Watch whether domestic truck-to-rail conversion keeps the volume firm as that import wave recedes. One near-term wrinkle in the West: A main line closed by flooding on October 24 and reopened October 26, so any dip in the Western networks next week reflects service, not demand.

Last week's scorecard
Last week we flagged three things. Here is how they played out.
-
Does intermodal spot keep going up? Barely. Spot added 0.2%, enough to extend the run but close to unchanged. After the climb through the quarter, this reads as a pause, not another leg up.
-
Is diesel starting another climb? Yes. Diesel gained a second straight week, up 7.6 cents to $6.352, putting the early-October pullback behind us. The slow retreat has turned around, and the year-over-year gap is back above 70%.
-
Will volumes still hold? They held and firmed. Year-to-date volume moved up to 3.7% in North America and 4.5% in the US, with the Western networks taking about two-thirds of the gain. The caution is international, where a front-loaded import run is set to turn down in November.
About the InTek Intermodal Index:
The InTek Intermodal Index (III) tracks weekly domestic intermodal spot rates on a per-mile basis, both including and excluding fuel surcharges. Each week's report includes comprehensive market analysis covering truckload pricing trends, diesel fuel costs, and railroad intermodal volumes to provide context for rate movements.
With rates tracked weekly since 2008, the Index serves as a resource for shippers, carriers, and industry analysts tracking North American freight market trends.
Citation: InTek Intermodal Index. (2026). Weekly Intermodal Spot Rate Report. Retrieved from https://www.inteklogistics.com/spot-rates
Want custom pricing for your lanes?
Get a tailored intermodal quote based on your specific shipping needs and freight profile.