![]()
InTek Intermodal Index (III) Week Ending Sept. 28, 2026
Weekly market intelligence including the InTek Intermodal Index (tracking intermodal spot rates), along with truckload pricing, diesel trends, and railroad volumes - Historical Edition
This Week at a Glance
Week ending September 28, 2026
Intermodal Spot Rate
(excluding fuel)
▲ +1.4% vs. last week
▲ +6.9% vs. last year
Truckload Spot Rate
(excluding fuel, DAT)
▲ +1.6% vs. last week
▲ +46.3% vs. last year
Diesel Fuel
(EIA National Average)
▼ -2.3% vs. last week
▲ +70% vs. last year
Intermodal Volume
(YTD vs. 2025)
U.S. ▲ +4.7%
North American ▲ +4%
This Week's Analysis
By Rick LaGore, CEO, InTek Logistics | September 28, 2026
Analysis of the InTek Intermodal Index (III) and freight market trends
Trends in the Intermodal Transportation Spot Rate and Market
Volume stepped up this week, and that's the change worth leading on. U.S. intermodal jumped to +4.7% year to date vs. 2025 - from 3.9%, the largest one-week move of the run. That volume jump comes as intermodal spot climbed 1.4% and diesel broke its three-week climb. For most of the quarter the story was firm pricing sitting on top of flat volume. This week the volume moved.
Intermodal spot now stands 6.9% above last year, a fifth gain in six weeks. The climb that's carried the annual reading from the low 4s to its current high-water mark is now joined by a volume move, which is the combination the framework watches for. Price firming while volume builds is intermodal confirming the market rather than pricing ahead of it. This is the first week price and volume have pushed the same direction with force. Whether it's a one-off or the start of a trend bears watching.
The demand question stays open underneath. Some of this week's volume is the late-peak push that was missing, and some is the conversion-and-cross-border story that has carried the year. The data does not yet separate the two. What changed is that the freight finally moved with the price instead of lagging it.
Both spot rates climbed this week, and both pushed their annual readings higher, so the mode comparison firmed across the board. The difference from recent weeks is the volume underneath. Intermodal freight stepped up with the price rather than lagging it, which is the piece that had been missing while rates ran on their own.
For shippers, the playbook holds. Price the spread on total landed cost with fuel in it. The fuel line is still the largest single item in the comparison, even with diesel easing this week, and where it goes next depends on refining margins more than on crude. Watch the 3-2-1 crack spread for that read.
InTek Intermodal Index (excluding fuel):
- Up 1.4% vs. prior week
- Up 6.9% vs. prior year
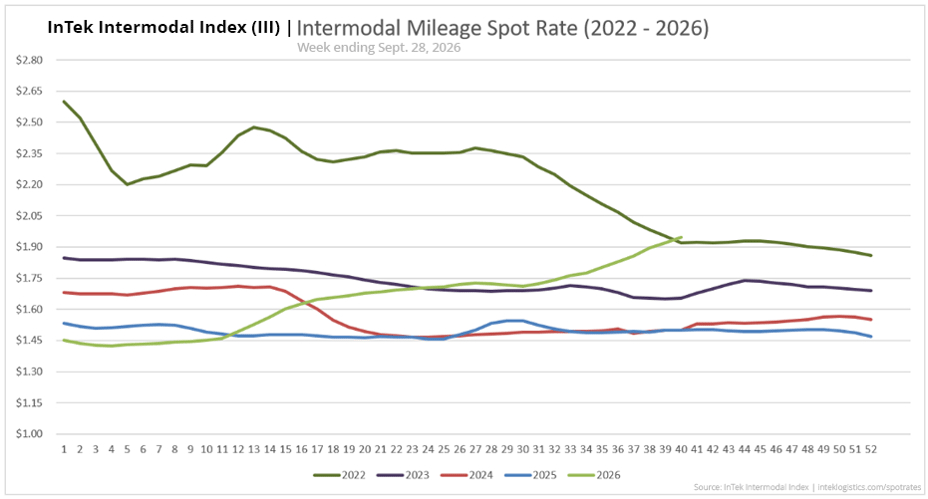
The InTek Intermodal Index (III), which tracks intermodal spot rates, rose 1.4% for the week and stands 6.9% above last year, the firmest annual reading of the year.
The gains continue their steady and additive pace - now across six weeks without a single spike. That gives the climb its durability. At 6.9%, intermodal's cost base is now well above a year ago, and the trend has held through peak instead of fading into it.
National Truckload Spot Rate (DAT, excluding fuel): (DAT Trendline Report)
- Up 1.6% vs. prior week
- Up 46.3% vs. prior year
Truckload spot climbed 1.6% for the week and jumped to 46.3% above last year from 42.4%. Both the weekly move and the annual step up point to a tightening peak on the truckload side. With both modes firming together, the linehaul spread held about even this week.
The premium to intermodal stays large, and truckload pushing back above 46% keeps the mode gap wide on lanes where both compete - without even getting into the diesel discussion.
Diesel Fuel (EIA):
- $6.382/gallon
- Down $0.147 (2.3%) vs. prior week
- Up $2.628 (70%) vs. prior year
Diesel broke its climb and eased to $6.382 per gallon, down 14.7 cents (2.3%) on the week, though it holds 70.0% above last year. This is the first decline in several weeks, coming right after diesel cleared $6.50. One down week is not relief, but the string of new highs paused.
Refining and distillate supply rather than crude remains the driver of high costs, and a single soft week does not confirm the tightness is easing. For a shipper, the 3-2-1 crack spread is what to watch for to determine where diesel goes next. Rail is roughly three times more fuel efficient than over-the-road truck on a ton-mile basis, so even after this week's dip, a 70% year-over-year diesel gap keeps the fuel line the largest single item in the mode comparison.
(The full spreadsheet of the historical weekly price moves of diesel full can be found at https://www.eia.gov/petroleum/gasdiesel.)
Year-to-Date Intermodal Volume by Region and Railroad vs. 2025
North American intermodal volume runs 4.0% ahead of 2025 year to date and US volume 4.7%, both stepping up (eight-tenths and a point) from last week. That is the largest one-week gain in the cumulative figures this run, and it answers the question that had been open all quarter. The freight moved with the price this week rather than sitting flat underneath it.
North American Intermodal
4%
U.S. Intermodal
4.7%
Volume by Railroad
| BNSF | 5.7% |
| CN | -2% |
| CPKC | 2% |
| CSX | 6.4% |
| GMXT | 14.6% |
| NS | 4.7% |
| UP | 2.2% |
Intermodal Spot Rate Trend Charts
Intermodal Spot Rate Per Mile (Including Fuel)
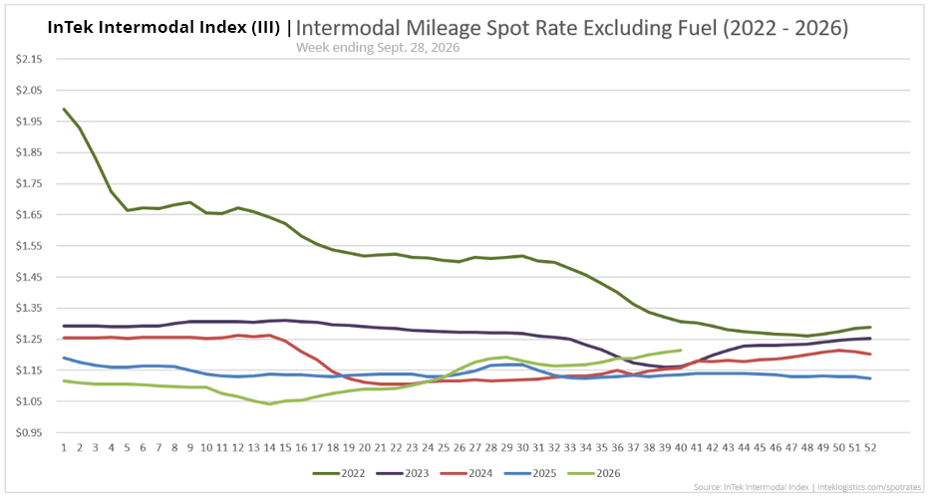
Intermodal Spot Rate Per Mile (Excluding Fuel)
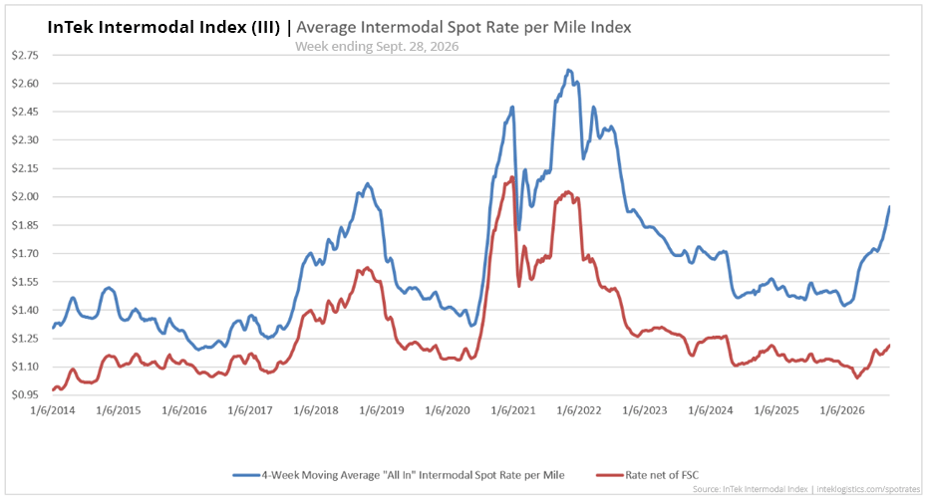
Intermodal Spot Rate Average Per Mile (2014-2026)
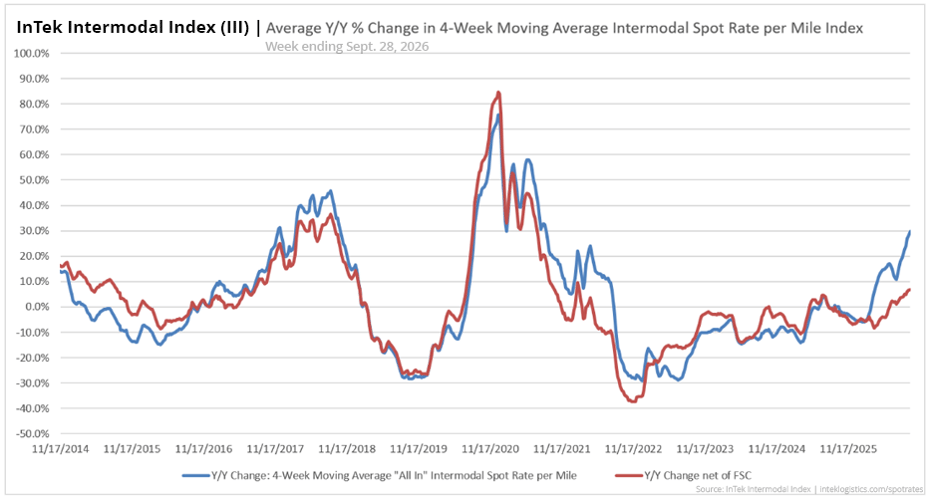
Intermodal Spot Rate Y/Y % Change (2014-2026)
What to watch next week
Three things to watch heading into the week of October 5, 2026.
Does the volume step hold?
U.S. volume jumped to 4.7% in one week after moving in tenths for a month. Watch whether the next print holds the gain or gives part of it back. A second week up would turn this from a late-peak push into a trend, and it would be the clearest confirmation signal of the year.
Is the diesel dip a pause or a turn?
Diesel eased for the first time in weeks after clearing $6.50. Watch the next EIA print and the crack spread. The run has reversed on a single week before and resumed, so one down print settles nothing. Refining stays tight and hurricane season is still open.
Does truckload keep pushing into peak?
Truckload jumped back above 46% year over year this week. Watch whether it holds that step up or settles. With both modes now firming on price and volume moving, the question is whether peak has real freight behind it or is still mostly a pricing event.

Last week's scorecard
Last week we flagged three things. Here is how they played out.
-
How long does the intermodal climb run? It's still running, so the answer is still TBD. Spot rose another 1.4% and pushed year-over-year to 6.9%, a fifth gain in six weeks. The climb has not leveled, and this week it picked up a volume move alongside it.
-
Where does diesel stop? It stopped, at least for now. Diesel eased 14.7 cents to $6.382 after clearing $6.50, its first decline in several weeks. The year-over-year gap is still 70%, so this is a pause in the run. Whether it becomes a break is yet to be seen.
-
Does volume stay flat while prices climb? No, and this is the week's real news. Volume stepped up across the board, with US intermodal jumping to 4.7% from 3.9%. The freight that had lagged the pricing all quarter finally moved with it.
About the InTek Intermodal Index:
The InTek Intermodal Index (III) tracks weekly domestic intermodal spot rates on a per-mile basis, both including and excluding fuel surcharges. Each week's report includes comprehensive market analysis covering truckload pricing trends, diesel fuel costs, and railroad intermodal volumes to provide context for rate movements.
With rates tracked weekly since 2008, the Index serves as a resource for shippers, carriers, and industry analysts tracking North American freight market trends.
Citation: InTek Intermodal Index. (2026). Weekly Intermodal Spot Rate Report. Retrieved from https://www.inteklogistics.com/spot-rates
Want custom pricing for your lanes?
Get a tailored intermodal quote based on your specific shipping needs and freight profile.