<img alt="" src="https://secure.perk0mean.com/182585.png" style="display:none;">

red-accent


InTek Intermodal Index (III) Week Ending Oct. 12, 2026
InTek Intermodal Index (III) Logo


Weekly market intelligence including the InTek Intermodal Index (tracking intermodal spot rates), along with truckload pricing, diesel trends, and railroad volumes - Historical Edition

→ Back to the archive

→ View the current edition

Get an intermodal quote

About-Hero-curve-1

This Week at a Glance

Week ending October 12, 2026

Train Truck Background Sketch-Light-Even

This Week's Analysis

By Rick LaGore, CEO, InTek Logistics | October 12, 2026

Analysis of the InTek Intermodal Index (III) and freight market trends

Trends in the Intermodal Transportation Spot Rate and Market

Intermodal spot rose again this week while truckload inched up and diesel sat near flat. The ex-fuel index gained 1.0% and 6.6% above last year. Truckload spot added 0.3% and holds 46.8% above last year. Diesel eased 2.0 cents to $6.179, a third week lower but barely, and it remains 68.6% above last year. US intermodal volume runs 4.2% ahead of 2025 year to date.

The week reads as a market holding its ground. Both spot rates ticked up, the diesel pullback nearly stopped, and volume stayed ahead of last year on conversion and cross-border freight. The quarter's open question is now the one that matters most, and it is a volume question. Does domestic truck-to-rail conversion hold the line as the import run that padded recent weeks rolls off into the fourth quarter.

InTek Intermodal Index (excluding fuel):

  • Up 1.0% vs. prior week
  • Up 6.6% vs. prior year

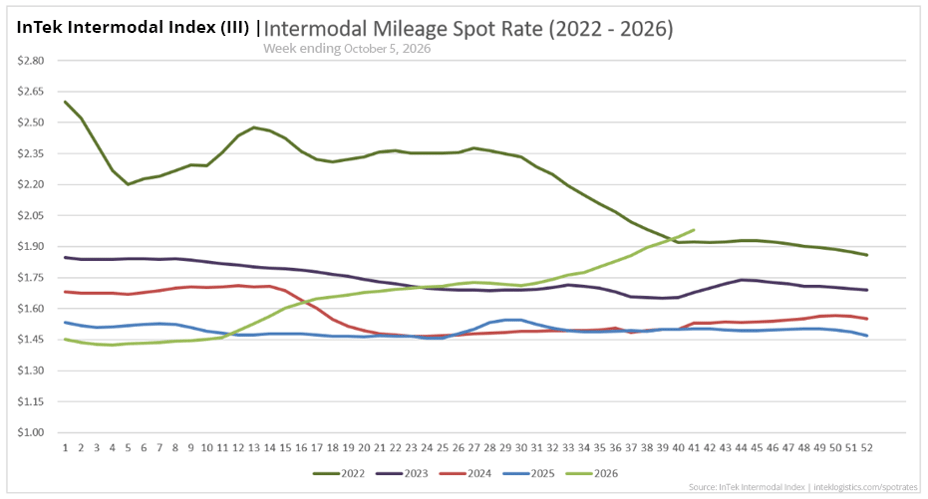
The InTek Intermodal Index (III), which tracks intermodal spot rates, rose 1.0% for the week and sits 6.6% above last year.  The weekly move is the signal to watch, and it continues to point up. Outbound California is tight on boxes and dray, which adds to the strength on West Coast lanes. Elsewhere, dray is where shippers see service strain, not the rail move itself.  


National Truckload Spot Rate (DAT, excluding fuel): (DAT Trendline Report)

  • Up 0.3% vs. prior week
  • Up 46.8% vs. prior year

Truckload spot added 0.3% for the week and holds 46.8% above last year. The weekly move is small, and the cost base well above last year keeps the mode gap wide on lanes where both compete. With intermodal rising alongside it, the linehaul spread held about even this week.

Gas Pump Sketch Light

Diesel Fuel (EIA):

  • $6.179/gallon
  • Down $0.020 (0.3%) vs. prior week
  • Up $2.514 (68.6%) vs. prior year

Diesel slipped 2.0 cents to $6.179 per gallon, down 0.3% on the week and up $2.514 (68.6%) on the year. This is a third week off the September high, but the pullback has nearly stopped. A 2-cent move is close to flat. The step down from $6.53 three weeks ago has slowed to a drift.

The driver has not changed. This run sits in refining and distillate supply, not in crude, and any retreat will track the same place. A move toward $5 would start to compress the truck-to-rail cost gap, the level worth watching from here, though most analysts put meaningful relief in 2027. Rail is roughly three times more fuel efficient than over-the-road truck on a ton-mile basis. At a 68.6% year-over-year gap, fuel keeps pulling marginal long-haul freight to rail.

(The full spreadsheet of the historical weekly price moves of diesel full can be found at https://www.eia.gov/petroleum/gasdiesel.)


Year-to-Date Intermodal Volume by Region and Railroad vs. 2025

North American intermodal volume runs 3.3% ahead of 2025 year to date and US volume 4.2%. The cumulative figures sit below the recent pace. A calendar shift around Labor Day pulls on the comparison, and the underlying growth rate reads firmer in the mid-single digits once that noise is set aside.

The growth is uneven by geography. Mexico cross-border is the standout, with GMXT at 10.1% year to date and running well higher on a recent basis as nearshoring routes more freight through that corridor. The Western US network holds the domestic growth, BNSF at 5.1% ahead of UP at 2.2%, though UP has climbed back to firmly positive. The Eastern carriers have slipped to the mid-single digits, CSX at 5.3% and NS at 4.0%. Both now trail the North American pace, the first sustained Eastern lag since spring. CPKC improved to 1.7% while CN at -2.6% remains the one carrier below last year.

One current underneath the figures is worth holding onto. Recent volume has carried an import boost alongside the conversion and cross-border story, and that import run is set to recede through the fourth quarter after an early-autumn peak. Whether domestic conversion holds the volume as the imports fall away is the quarter's real test.

North American Intermodal

3.3%

U.S. Intermodal

4.2%

Volume by Railroad

BNSF 5.1%
CN -2.6%
CPKC 1.7%
CSX 5.3%
GMXT 10.1%
NS 4.0%
UP 2.2%


Dark-blue-curve-up

Intermodal Spot Rate Trend Charts

InTek Intermodal Index (III) spot rate per mile including fuel, showing weekly trends

Intermodal Spot Rate Per Mile (Including Fuel)
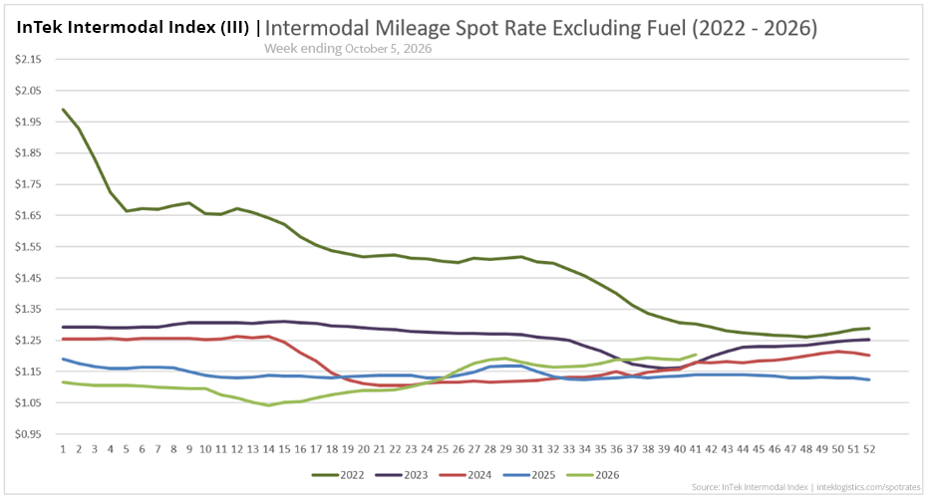
  

InTek Intermodal Index (III) spot rate per mile excluding fuel, showing weekly trends

Intermodal Spot Rate Per Mile (Excluding Fuel)
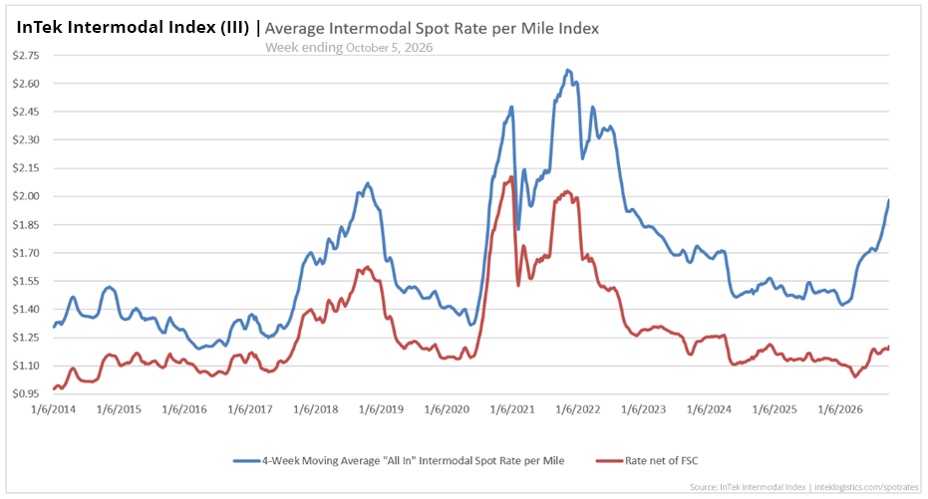
 

InTek Intermodal Index (III) average intermodal spot rate per mile from 2021 to 2026 Intermodal Spot Rate Average Per Mile (2014-2026)
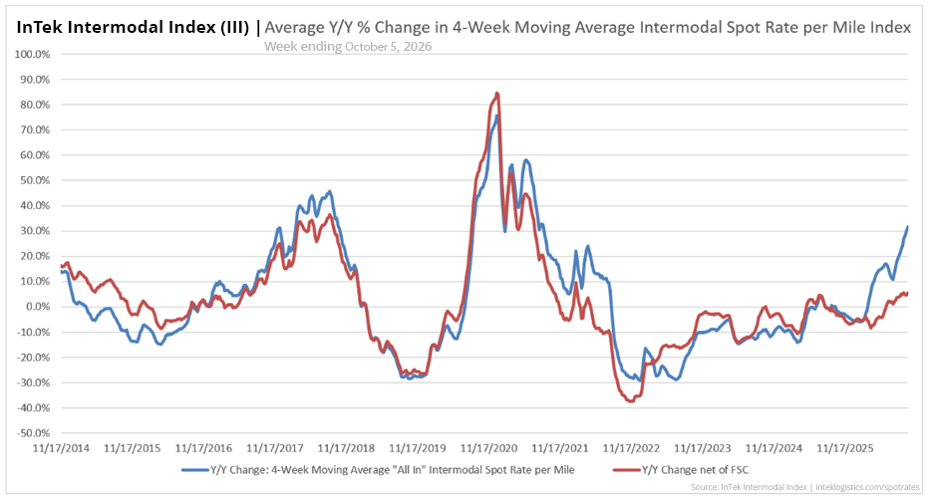
InTek Intermodal Index (III) average intermodal percentage rate change per mile from 2021 to 2026

Intermodal Spot Rate Y/Y % Change (2014-2026)
medium-blue-curve-down-right

What to watch next week

Three things to watch heading into the week of October 19, 2026.

Last week's scorecard

Last week we flagged three things. Here is how they played out.

  • Does domestic conversion hold as imports recede? Too early to read, and the test has not arrived. Imports stayed firm rather than receding, with the seasonal peak only now behind us, so the import boost that padded recent volume is still in the numbers. Conversion and cross-border held the line underneath, and US year-to-date volume improved to 4.2%. The question carries into the fourth quarter intact.

  • How fast does diesel retreat? Slowly, and this week it nearly stopped. Diesel gave back just 2.0 cents to $6.179 after an 18-cent drop the week before. The pace has gone from a step down to a drift, and nothing points toward $5 yet.

  • Does truckload keep pushing into peak? Yes, but just barely.

About the InTek Intermodal Index:

The InTek Intermodal Index (III) tracks weekly domestic intermodal spot rates on a per-mile basis, both including and excluding fuel surcharges. Each week's report includes comprehensive market analysis covering truckload pricing trends, diesel fuel costs, and railroad intermodal volumes to provide context for rate movements.

With rates tracked weekly since 2008, the Index serves as a resource for shippers, carriers, and industry analysts tracking North American freight market trends.

Citation: InTek Intermodal Index. (2026). Weekly Intermodal Spot Rate Report. Retrieved from https://www.inteklogistics.com/spot-rates

Divider


Want custom pricing for your lanes?

Get a tailored intermodal quote based on your specific shipping needs and freight profile.